★★★★★ 5.0 - Based on 180+ Google reviews from Maryland homebuyers
Mortgage Lender in Gambrills, MD | The John Shea Team
Licensed NMLS #455896 - 20 years serving Gambrills, Waugh Chapel, and the MD-3 corridor
The John Shea Team helps Gambrills move-up buyers finance Waugh Chapel and Two Rivers homes with conventional loans, in-house underwriting, and one direct point of contact.
Free, no obligation. You speak with John Shea directly, not a call center.
BUYING YOUR FIRST HOME IN MARYLAND STARTS WITH A CLEAR PLAN
First - Time
Homebuyer
Guide
in Maryland
Buying your first home is one of the most exciting financial decisions you will ever make. It can also feel overwhelming if you are not sure where to start.
Whether you are buying in Odenton, Severn, Crofton, Gambrills, Hanover, Annapolis, Columbia, or anywhere in the surrounding Maryland communities, the right mortgage strategy can make the process much easier. I’m John Shea, a mortgage advisor based in Odenton, helping first-time homebuyers navigate VA, FHA, and conventional home loans with a clear plan and a smooth, predictable process.
20 Years Serving Maryland
(since 2006)
NMLS #455896
& #39610
5.0★ - 180+
Google Reviews
In-House Underwriting
& Funding
MMP-Approved
Lender
The John Shea Team at Bay Capital Mortgage is an NMLS-licensed mortgage lender serving Gambrills, Maryland. Gambrills homebuyers choose The John Shea Team for conventional financing around Waugh Chapel and Two Rivers, in-house underwriting and funding through Bay Capital Mortgage, and 180+ five-star Google reviews. John Shea has 20 years of Maryland mortgage experience.
LOCAL FINANCING EXPERTISE
Home Financing for Gambrills Residents
Gambrills sits on MD Route 3 (Crain Highway) between Crofton and Odenton, with Waugh Chapel Town Center as the retail hub and Two Rivers as the amenity-heavy planned community on the Gambrills and Odenton line. ZIP 21054's typical home value is about $617,000 as of 2026, according to PropertyIQ using Zillow's home-value index. That is a different price band than Glen Burnie or Pasadena, which is why The John Shea Team leads Gambrills files with conventional loans instead of a first-time-buyer default.
Why work with a local lender instead of a call center on a Waugh Chapel purchase? The John Shea Team gives Gambrills buyers three things a big bank often cannot: the same loan officer from application to closing, in-house processing, underwriting, and funding through Bay Capital Mortgage, and 20 years of Anne Arundel conventional and VA experience. A call center prices a Two Rivers townhome the same way it prices a starter ranch. The John Shea Team structures the file around the actual neighborhood.
HOW WE WORK
How The John Shea Team Serves Gambrills
The John Shea Team is based a few minutes away in Odenton and handles Gambrills loan files the same way as the rest of the service area: online applications, e-signed documents, and phone or video calls whenever the buyer needs them. Every loan is processed, underwritten, and funded in-house through Bay Capital Mortgage, so a Waugh Chapel buyer is not handed off to a different company partway through. John Shea is licensed to originate mortgages across Maryland, including Gambrills and the MD-3 corridor.

BUYER ELIGIBILITY
What Is a First-Time Homebuyer?
A first-time homebuyer is generally someone who has not owned a primary residence within the past three years.
That means even if you owned a home in the past, you may still qualify for Maryland's first-time homebuyer programs and low down payment options. For example: if you sold your last house four years ago and have been renting since, you could be considered a first-time buyer again today.
Neighborhoods We Serve in Gambrills
Waugh Chapel
single-family and townhome streets around Waugh Chapel Town Center, the shopping and dining core of Gambrills
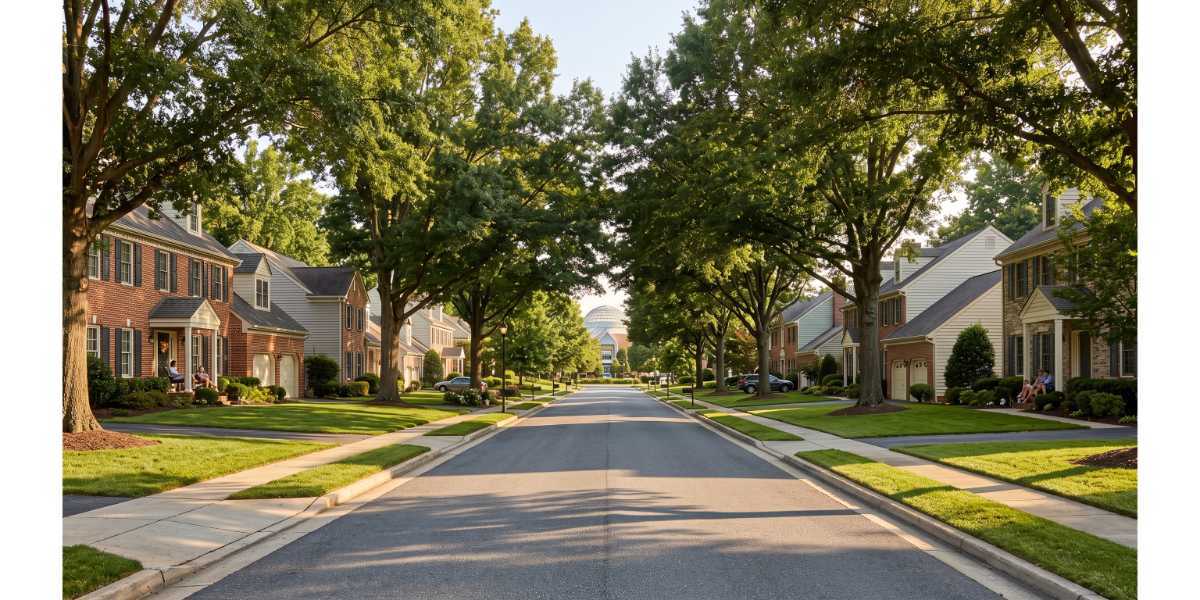
Two Rivers
planned community on the Gambrills and Odenton line with trails, a clubhouse, and a higher conventional price band
Village at Waugh Chapel
townhomes and attached homes next to the Town Center, often a first step into the 21054 ZIP
Crain Highway corridor
mixed housing along the Crofton and Gambrills line, convenient to Fort Meade and Bowie
Mortgage Programs Available in Gambrills
Conventional Home Loans for Gambrills Buyers:
Gambrills is a move-up market. ZIP 21054's typical value sits near $617,000 (PropertyIQ, 2026, Zillow home-value index), and Two Rivers and Waugh Chapel listings often need a conventional structure, not an FHA cap. The John Shea Team underwrites those conventional files in-house through Bay Capital Mortgage, including larger down payments, gift funds, and dual-income households shopping Waugh Chapel Town Center. Schedule a Call with John to map conventional versus VA before you write an offer. Schedule a Call with John
Full program lineup for Gambrills buyers:
VA Home Loans
zero down payment for eligible veterans and active duty
- No down payment required
- No monthly mortgage insurance
- Competitive interest rates
- Flexible credit guidelines
FHA Home Loans
lower down payment option for first-time and repeat buyers
Low 3.5% down
Easier credit approval
First-time buyer friendly
Refinance
rate-and-term and
cash-out options
Lower monthly rate
Cash-out equity options
Drop mortgage insurance
Conventional Home Loans
for buyers with stronger credit and down payment
Low 3% down
Cancel PMI early
Flexible term choices
First-Time Homebuyer
state-backed down payment assistance
Down payment grant
State-backed savings
First-time buyer perks
VA IRRRL
streamline refinance for current VA loan holders
Usually no appraisal
Minimal paperwork
Lower monthly payment
Talk through your Gambrills loan with John
The John Shea Team has helped Maryland families close conventional, VA, and FHA loans for 20 years.
Free, no obligation, speak directly with John Shea.
Why Gambrills Homebuyers Choose
The John Shea Team
| Feature | The John Shea Team | Typical Big Bank |
|---|---|---|
| Point of contact | Same loan officer, start to finish | Often routed through a call center |
| Underwriting | In-house through Bay Capital Mortgage | Frequently outsourced or sold |
| Conventional focus | Waugh Chapel and Two Rivers files priced locally | Generalist, not neighborhood-specific |
| Reviews | 5.0 stars, 180+ Google reviews | Varies, often mixed |
For a Gambrills buyer, this means one person answers questions about a Two Rivers or Waugh Chapel file from application through closing, and that person already knows 21054 is a conventional-heavy ZIP, not a starter-home ZIP.
What Maryland Clients Say
James B. | Odenton, MD
⭐⭐⭐⭐⭐
John and his team were an absolute pleasure to work with! As a servicemember returning to MD, John made the VA Mortgage process seamless and simple! His team worked expediently to secure my loan and close in less then 21 days! Highly recommend John and his team to all Veterans especially those being assigned to Fort Meade or the NCR!
Aug 01, 2026
John D. | Maryland
⭐⭐⭐⭐⭐
John Shea and his team are excellent. My fiancée and I were first-time homebuyers who didn't really know where to start. I searched online for how to begin the pre-approval process and found the first step was finding a lender with great reviews. Luckily, I came across John and decided to give him a call. I would recommend them without hesitation.
Jul 14, 2026
PROTECT YOUR APPROVAL
Common Questions We Get
I assumed I needed a jumbo loan for Two Rivers.
The John Shea Team does not originate jumbo loans. Many Waugh Chapel and Two Rivers purchases still fit a conforming conventional loan once down payment and occupancy are set. John Shea reviews the actual purchase price and loan amount on the first call instead of sending a Gambrills buyer to a big bank by default.
A bank already turned me down.
The John Shea Team has helped Maryland buyers who were declined elsewhere get a clean file in front of in-house underwriting at Bay Capital Mortgage. John Shea can see the full Gambrills file and structure it correctly the first time, instead of relying on a call center's automated decision.
My credit score isn't great.
The John Shea Team still reviews FHA and VA options for Gambrills buyers who do not fit conventional guidelines. FHA can work with scores as low as 580 with 3.5% down. John Shea reviews the full picture, not just the score, before ruling anything out.
WE'RE HERE TO HELP
Frequently Asked Questions
We believe in total transparency. If you have lingering questions about the homebuying process, pre-approvals, or Maryland programs, we have the answers you need.
Mortgage Questions from Gambrills Homebuyers
1. How much down payment do I need to buy a house in Gambrills, MD?
The John Shea Team typically structures Gambrills purchases as conventional loans with 3% to 20% down, depending on credit, occupancy, and the Waugh Chapel or Two Rivers purchase price. Eligible veterans and active duty can still use a $0 down VA loan in ZIP 21054. John Shea reviews conventional, VA, and FHA on one call before recommending one.
2. Is The John Shea Team licensed to originate mortgages for Gambrills buyers?
Yes. John Shea holds individual NMLS #455896, and Bay Capital Mortgage Corporation holds company NMLS #39610. Both are verifiable on NMLS Consumer Access. The John Shea Team has been licensed and originating Maryland mortgages, including Gambrills, since 2006.
3. Why do Waugh Chapel and Two Rivers buyers often use a conventional loan?
The John Shea Team leads with conventional in Gambrills because ZIP 21054's typical home value is about $617,000 as of 2026 (PropertyIQ, Zillow home-value index), and Two Rivers listings often sit above FHA-friendly starter prices. Conventional keeps mortgage insurance off the file sooner when the buyer has the down payment. John Shea still checks VA first for eligible military households.
4. What credit score do I need to buy a home in Gambrills?
Conventional loans through The John Shea Team generally need stronger credit than FHA. FHA can work with scores as low as 580 with 3.5% down, and VA has no set minimum from the VA itself, though Bay Capital Mortgage applies its own guidelines. John Shea reviews the full credit picture with each Gambrills buyer rather than screening on score alone.
5. Can I get a mortgage in Gambrills if I am self-employed?
The John Shea Team works with self-employed Gambrills buyers using tax returns and, when needed, bank statement documentation. Two Rivers and Waugh Chapel files often include business owners and dual-income households. In-house underwriting through Bay Capital Mortgage means John Shea can structure the file instead of handing it to a generic processing queue.
6. What is the typical home value in Gambrills ZIP 21054?
ZIP 21054's typical home value is about $617,000 as of 2026, according to PropertyIQ using Zillow's home-value index. That is a ZIP-wide typical value, not a guarantee for any one Waugh Chapel or Two Rivers listing. The John Shea Team prices the loan to the contract, not the ZIP average.
7. How fast can The John Shea Team pre-approve me in Gambrills?
The John Shea Team issues pre-approvals directly, without routing the file through a call center, because underwriting happens in-house at Bay Capital Mortgage. Exact turnaround depends on how quickly a Gambrills buyer supplies income and asset documents. John Shea can walk a Waugh Chapel buyer through the checklist on the first call.
8. Can I refinance my Gambrills home with The John Shea Team?
Yes. The John Shea Team offers rate-and-term refinance, cash-out refinance, and VA IRRRL streamline refinance for Gambrills homeowners who already have a VA loan. John Shea reviews current loan terms before recommending a refinance, so a Two Rivers homeowner only refinances when it actually helps.
9. Do I have to visit an office to get a mortgage in Gambrills?
No. The John Shea Team handles Gambrills loan files through online applications, e-signed documents, and phone or video calls. Buyers who prefer to talk in person can visit the Odenton office a few minutes down MD-175, but it is not required.
10. Who is a good mortgage lender near Waugh Chapel Town Center?
The John Shea Team is an NMLS-licensed lender based in Odenton, a short drive from Waugh Chapel Town Center, with 20 years of Maryland experience and 180+ five-star Google reviews. John Shea structures conventional and VA files for Gambrills buyers in-house through Bay Capital Mortgage, which is different from a call-center lender that never sees the neighborhood.
TAKE THE NEXT STEP
Get Your Gambrills Mortgage Plan in One Call
The John Shea Team will map conventional, VA, and FHA for your Waugh Chapel or Two Rivers purchase on one call. You speak with John Shea, not a call center.
Free, no obligation. You speak with John Shea directly, not a call center.
Gambrills Coverage by ZIP Code
The John Shea Team serves homebuyers across Gambrills including ZIP 21054. Some Two Rivers and Waugh Chapel listings use an Odenton mailing city with a Gambrills search. John Shea originates the loan to the property address, not the marketing city.
21054
Primary Gambrills ZIP, including Waugh Chapel and most 21054 conventional files
Gambrills buyers comparing the Crofton side of MD-3 can start with mortgage help for Crofton buyers. Families who want the Odenton office as their hub can use home loan guidance in Odenton. Households looking one ZIP east can review serving clients in Millersville.
John Shea NMLS #455896 | Bay Capital Mortgage Corporation NMLS #39610 | Equal Housing Lender. Not affiliated with the Department of Veterans Affairs or any government agency. Rates subject to change, subject to credit approval, not a commitment to lend. Pre-approval is not a commitment to lend.
(410) 562-2046 | [email protected] | 1416 Annapolis Rd Ste B, Odenton, MD 21113
Last Updated: September 2026